
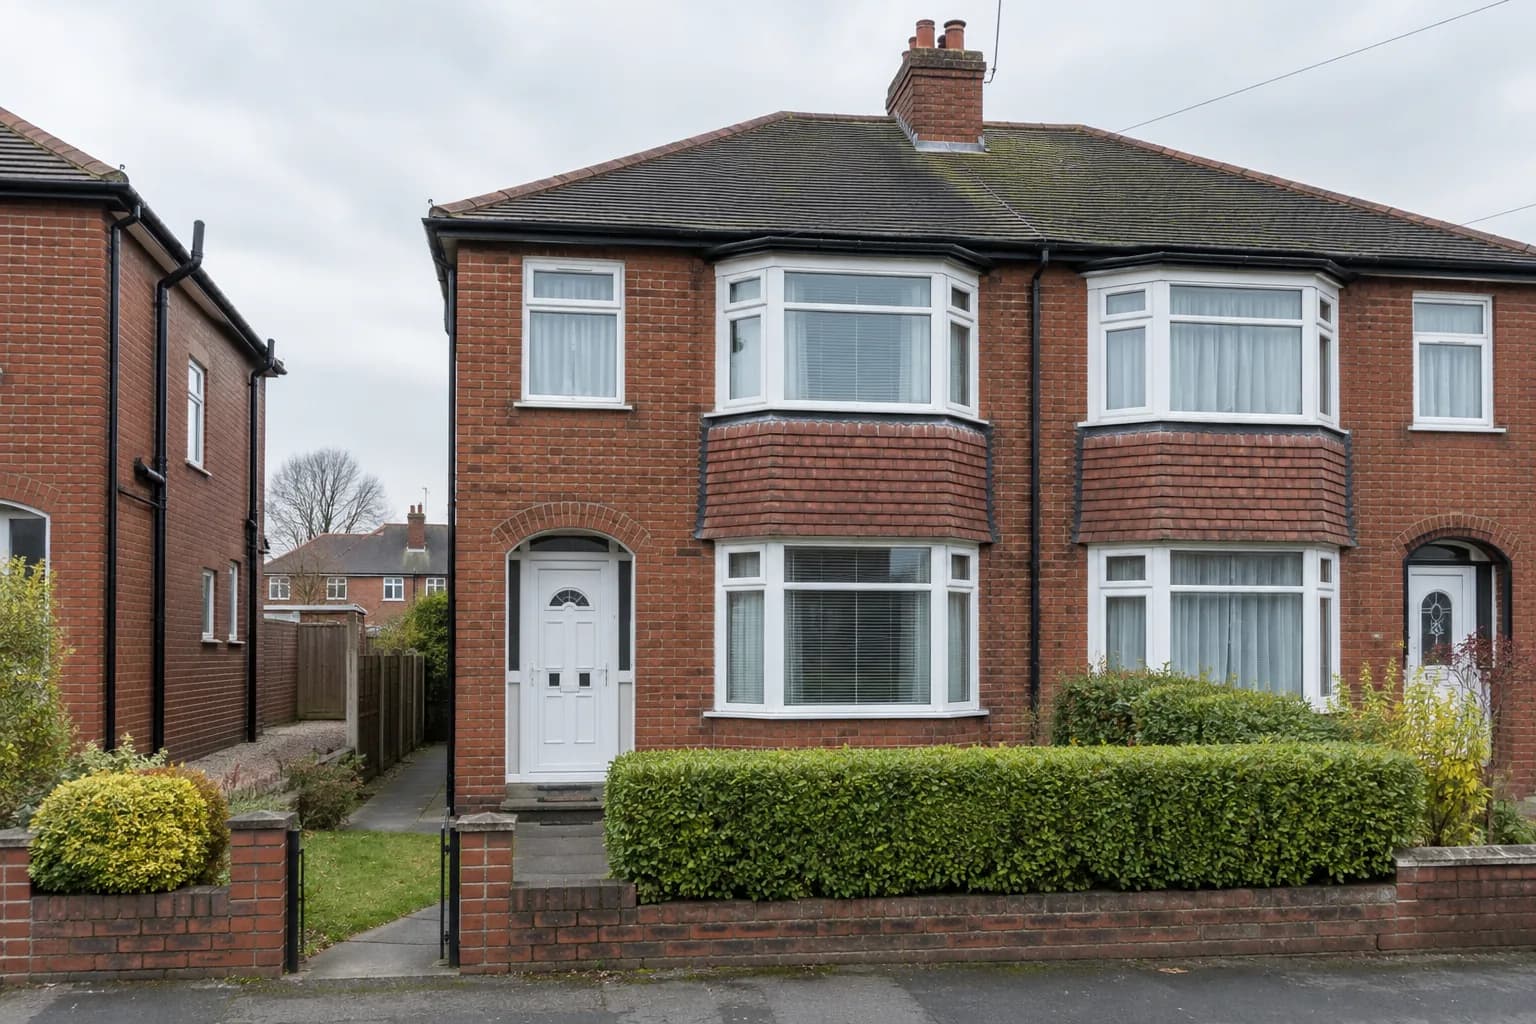
Cross Green Lane, Leeds
Know when to walk away.
An attractive property can still be the wrong purchase. At this asking price, the rent does not cover the modelled costs, and repairs could make the shortfall worse.
Move on at the current price. Revisit only if the price changes enough to justify a fresh survey and calculation.
- Asking price
- £265,000
- Cash needed upfront
- £120,150
- Monthly cashflow
- -£23/mo
No discount assumed
Deposit, works, stamp duty and buying fees
After mortgage and running costs, before tax
01 / The numbers
Does the margin hold up?
At the asking price. Even the base case leaves a monthly shortfall.
Where the rent goes
Per monthThe assumptions in this sample report
-£23/moShortfall before tax in the base case
75% interest-only borrowing, 5.4% base interest, 8% management and 6% voids/maintenance. Other running costs stay fixed. Figures are rounded; taxes and costs depend on your circumstances.
Your cash commitment
Before refinance£120,150Upfront cash
- Deposit
- £66,250
- Works
- £32,000
- Stamp duty
- £16,500
- Buying fees
- £5,400
Borrowing covers the balance of the purchase price. Keep an additional reserve for overruns and costs not yet identified.
02 / The judgement
The upside. And the unanswered questions.
The sample's asking price sits above its sold comparables while cashflow is negative. The appearance of a property cannot repair that gap.
What supports the case
- Presentation is decent enough to tempt a buyer chasing the surface-level story
- Standard three-bed layout looks straightforward on first inspection
- The pass decision is defensible and easy to communicate to partners
What could change the decision
- Cashflow remains negative across realistic scenarios.
- Premium to sold evidence has no supporting justification.
- Condition risk could erase any remaining margin.
What to check next
- Walk away at the current ask
- Only reopen if the price resets hard
- If it comes back, survey it as a heavy refurb